

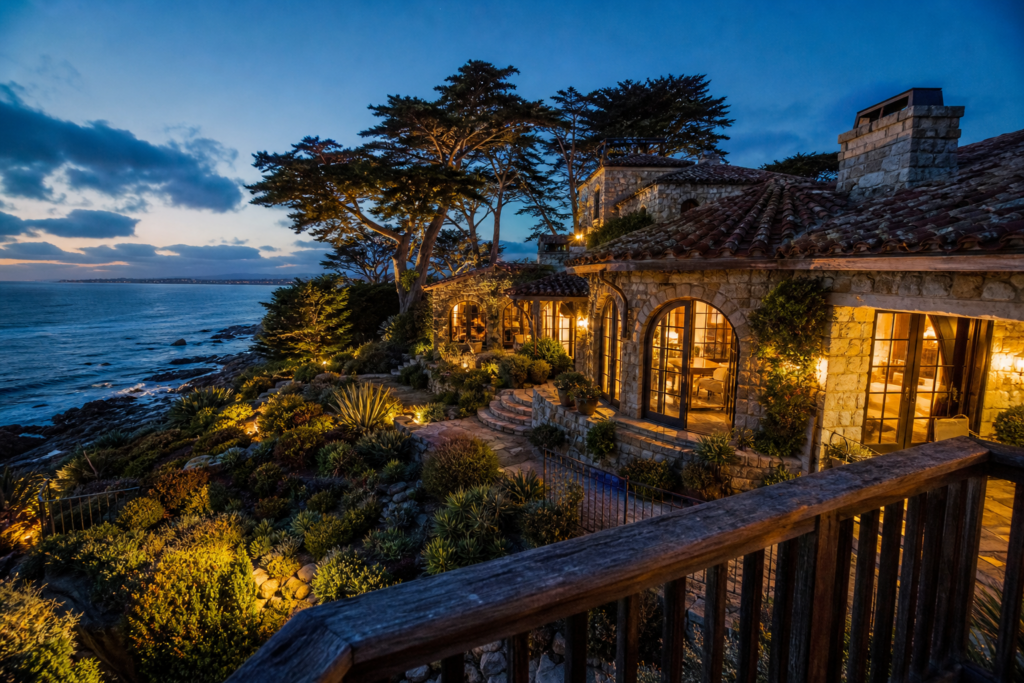
What are the biggest risks of buying a high-end investment property in Carmel-by-the-Sea in 2026 given coastal erosion concerns and insurance market instability?
The two greatest risks are spiraling insurance costs that can destroy your projected returns and physical coastal erosion that threatens both the structure and future resale liquidity of bluff-top and oceanfront properties in Carmel-by-the-Sea.
Why Carmel-by-the-Sea Investment Risk Matters Right Now
If you have been eyeing a luxury investment property along Scenic Road or anywhere near the Carmel coastline, 2026 is a year that demands a different kind of underwriting than what may have worked even three years ago. The California insurance market has fundamentally shifted. Construction costs keep climbing. And the Pacific Ocean does not care about your pro forma.
Carmel-by-the-Sea has always been an ultra-luxury coastal enclave with strict development controls and short-term rental restrictions, which have kept supply tightly constrained. But the layered risks emerging in 2026, from insurance carrier withdrawals to accelerating bluff erosion, have changed the calculus for investors. What I tell my clients is straightforward: you can still make a smart investment in Carmel, but only if you underwrite the risks that most buyers still overlook.
Let me walk you through each one.
The Carmel-by-the-Sea Insurance Crisis Is Not Just a Headline
This is the single most important risk factor you need to understand before writing a check for a high-end Carmel property. Here is the reality: since 2022, 7 of the top 12 home insurance companies in California, representing roughly 85% of the homeowners’ market, have paused or restricted new business in the state, according to data compiled by the California Association of REALTORS. That is not a temporary blip. That is a structural withdrawal of private capital from the market.
What This Means for Your Carmel Investment
For a luxury coastal property where replacement cost is already elevated, the consequences are severe:
- You may not be able to get private coverage at all. Obtaining adequate insurance for a high-value oceanfront home in Carmel-by-the-Sea has become a material contingency in transactions, not a rubber-stamp formality.
- At luxury price points, these percentages translate into enormous dollar amounts. When your replacement cost runs into the millions, an 11% rate increase is not a rounding error. It is a line item that can fundamentally change your cap rate.
So what does that actually mean for your bottom line? It means you need to get binding insurance quotes before you finalize any offer, not after. And you need to model at least three to five years of continued premium escalation into your hold-period projections.
The FAIR Plan Fallback in Carmel-by-the-Sea Is Not What You Think
Many investors assume that if private insurance is unavailable, the California FAIR Plan will serve as a reliable backup. That assumption is dangerous.
The FAIR Plan is the state’s insurer of last resort, covering people who cannot get private insurance because their properties are deemed too risky. As of mid-2025, the FAIR Plan carried roughly 590,642 residential policies, more than double its count from just a few years prior, according to an October 2025 C.A.R. analysis. That explosive growth tells you something important: this was never designed to be the primary insurer for hundreds of thousands of homes.
Why FAIR Plan Coverage Falls Short for Luxury Carmel Properties
- Cost: FAIR Plan coverage often runs two to three times the cost of traditional private policies, per C.A.R. reporting from October 2025.
- Limited protection: The FAIR Plan typically offers only basic fire protection, meaning you would likely need supplemental coverage on top of it, adding further expense and complexity.
- Rate hikes are coming: Under a proposed restructuring, about 4 in 5 FAIR Plan homeowner policyholders would face rate increases, with the majority of hikes ranging from 5% to 60%, according to the same October 2025 C.A.R. data.
- Lender complications: If your lender has specific coverage requirements, a bare-bones FAIR Plan policy may not satisfy them — confirm coverage acceptability with your lender and loan officer before closing.
The mistake I watch investors make here is treating insurance as an afterthought. In Carmel-by-the-Sea in 2026, insurance availability and cost should be your first due-diligence item, not your last.
Coastal Erosion Risks Along the Carmel-by-the-Sea Shoreline
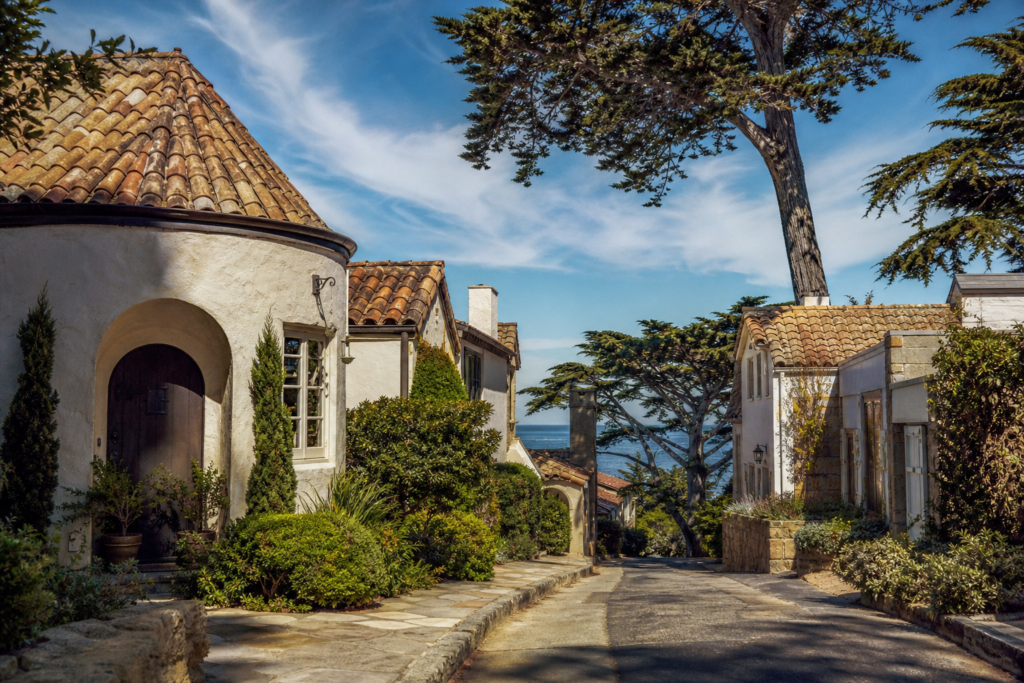
The physical risk is just as real as the financial one. Sea-level rise has the potential to affect coastal residents, recreation, and development in communities like Carmel-by-the-Sea, where bluff-top homes along Scenic Road and oceanfront properties near Carmel Beach face direct exposure.
The Specific Hazards You Need to Evaluate
According to guidance from the California Association of REALTORS, coastal property risks include:
- Shoreline, beach, and bluff erosion that can undermine foundations and reduce usable lot area over time
- Questions about the effectiveness of seawalls and bulkheads, which may or may not provide long-term protection depending on the specific geology
- Restrictions on seaward construction or improvement to existing structures, which can limit your renovation or expansion plans
- The potential enactment of geological hazard abatement districts and associated assessments, which create ongoing costs
- Determination of the mean high tide line, which directly affects where your property boundary actually sits, and that line can shift
What does this mean in practice? It means a property that looks like a dream investment today could face significant physical impairment over a 10- or 15-year hold period. And unlike a leaky roof, you cannot fix the ocean.
Due Diligence Is Non-Negotiable in Carmel-by-the-Sea
Buyers of coastal Carmel properties are advised to consult with appropriate professionals, including having a geological inspection to identify the effect of coastal conditions on the property, per C.A.R. buyer advisory guidance. Any construction or development on affected properties may be subject to the findings of a geological report prepared by a registered California geologist. You should treat a geological inspection and a coastal hazard assessment as important line items in your due-diligence budget.
How Reinsurance Stress and Construction Inflation Compound Your Carmel Risk
Even if you secure private insurance today, the systemic forces behind the crisis are not easing. The reinsurance market, where primary insurers offload their own risk, is showing signs of stress following the Southern California wildfire events, contributing to further rate pressure across the state according to C.A.R. analysis.
At the same time, rising construction costs are amplifying the problem. Demand for both materials and skilled labor continues to outstrip supply, which means your replacement-cost coverage requirements keep climbing even if the property itself does not change.
For a luxury Carmel-by-the-Sea property, here is how these forces compound:
- Higher replacement costs mean you need more coverage
- More coverage at higher per-unit rates means dramatically higher premiums
- Higher premiums reduce your net operating income
- Reduced NOI compresses your effective cap rate
- Compressed cap rates make it harder to justify the acquisition price
This is not a theoretical exercise. If you are modeling a seven-figure acquisition in Carmel-by-the-Sea, the difference between current-year insurance costs and what you might be paying in year three or four of your hold period could be the difference between a profitable investment and an expensive lesson.
Carmel-by-the-Sea Regulatory and Disclosure Risks for Investors
Beyond the physical and insurance risks, Carmel-by-the-Sea presents a regulatory environment that investors must understand before committing capital.
Development Controls and Short-Term Rental Restrictions
Carmel-by-the-Sea is known for its strict development controls and limitations on short-term rentals. If your investment thesis depends on Airbnb-style income or significant property modifications, you need to verify feasibility with the city before closing. The constrained supply that supports property values in Carmel also constrains what you can do with your investment once you own it.
Disclosure Obligations Add Time and Cost
The transaction complexity for coastal Carmel properties is higher than for inland luxury homes. Geological reports, coastal hazard assessments, and enhanced disclosure requirements all add time and cost to your acquisition process. If you are planning renovation or structural improvements, the findings of a geological report can materially affect project timelines and feasibility.
What I consistently see in this market is investors who budget for the purchase price but fail to budget for the due-diligence process itself. In Carmel-by-the-Sea, that process is more expensive and more time-consuming than you might expect, and skipping steps can expose you to liabilities that dwarf the savings.
Frequently Asked Questions About Carmel-by-the-Sea Investment Risks in 2026
Can you still get private homeowner insurance for a Carmel-by-the-Sea property in 2026?
It depends on the specific property, its location relative to the coastline, and the insurer. Since 2022, 7 of the top 12 California home insurers have paused or restricted new business, per C.A.R. data. You should obtain binding insurance quotes as a condition of your offer, not after you are under contract.
How much could insurance cost for a luxury Carmel coastal property?
Exact premiums vary by property, but the trajectory is steep. Under the AAA rate filing as of May 2026, some policyholders could see premiums rise from roughly $1,650 to approximately $13,100 annually, per C.A.R. reporting. At luxury replacement-cost levels, the numbers can be significantly higher.
What is the California FAIR Plan and should I rely on it in Carmel?
The FAIR Plan is the state’s insurer of last resort for properties private companies will not cover. It typically costs two to three times as much as traditional policies and provides only basic fire protection, according to October 2025 C.A.R. analysis. For a high-value Carmel property, it is a costly and limited fallback, not a solution.
Is coastal erosion already priced into Carmel-by-the-Sea property values?
That is the critical question, and the honest answer is: unknown — no market data exists to answer this question definitively. Many investors underestimate how quickly coastal conditions can change and how disclosure and geological requirements can affect future buyers’ willingness to pay. This represents a potential tail risk to your exit assumptions.
Do I need a geological inspection before buying coastal property in Carmel?
Yes — C.A.R. buyer advisory guidance advises buyers to consult with appropriate professionals, including having a geological inspection, to identify the effect of coastal conditions on the property. Separately, construction or development on affected properties may be subject to the findings of a geological report prepared by a registered California geologist. Treat this as an important due-diligence expense.
Can I do short-term rentals in Carmel-by-the-Sea?
Carmel-by-the-Sea has strict limitations on short-term rentals. If your investment thesis depends on vacation rental income, you need to verify current regulations with the city before making an offer. Do not assume you can operate the way you might in other coastal markets.
How does reinsurance stress affect my Carmel property investment?
Reinsurance market stress following major wildfire events is contributing to primary rate increases statewide, per C.A.R. analysis. This means even if you secure favorable coverage today, systemic pressure could push your premiums higher in subsequent years, compressing your returns.
What happens if my insurance carrier pulls out of California after I buy?
This is a real risk. If your carrier exits or non-renews, you may be forced onto the FAIR Plan or into a surplus-lines market at significantly higher cost. Build this scenario into your financial modeling before you close.
Are seawalls effective at protecting Carmel bluff properties long-term?
Effectiveness varies by specific geology and construction. C.A.R. guidance notes that the effectiveness of seawalls and bulkheads is one of the specific coastal issues buyers should evaluate. A qualified coastal engineer can assess your specific property, but no seawall provides a permanent guarantee.
Should I still consider investing in Carmel-by-the-Sea given these risks?
The risks are real but so is the long-term appeal of an extremely supply-constrained luxury coastal market. The key is rigorous underwriting: get insurance quotes first, commission geological assessments, model premium escalation over your hold period, and verify your renovation plans are feasible under local regulations.
The Bottom Line on Carmel-by-the-Sea Investment Risk in 2026
Carmel-by-the-Sea remains one of California’s most desirable luxury enclaves, and that is precisely why the stakes are so high. The convergence of insurance market instability, rising premiums, coastal erosion exposure, and strict local regulations means your due-diligence process in 2026 needs to be more thorough than it has ever been. Insurance availability should be your first phone call, not your last. Geological assessments are not optional. And your financial projections must account for years of premium escalation, not just today’s quote. If you are evaluating Santa Cruz County investment properties or luxury coastal acquisitions in the broader Monterey Bay area and want someone who will give you straight answers about the real risks, reach out to Mario Desantis, Founder of Desantis Realty Group and REALTOR with Coldwell Banker Realty (CA DRE #02119587). You can call (831) 291-0511 or visit desantisrealty.com.
*Mario Desantis, REALTOR®, Coldwell Banker Realty, CA DRE #02119587. Equal Housing Opportunity. This content represents opinion of value and general market commentary. It is not an appraisal and does not guarantee any outcome. Consult a licensed insurance professional, attorney, or tax advisor for guidance specific to your situation.*
